

Andrew Pickett Law is a top Titusville car accident law firm that handles crash cases throughout Titusville and North Brevard County for victims who need help getting medical treatment and financial recovery. In review after review, clients say the firm kept them in the loop the whole way through.
What You Need To Know
- A car accident claim has more moving parts than it looks like from the outside, and you and the insurance company settle most of those parts in the first few weeks. A lawyer who handles car claims every day keeps the moving parts from being decided against you.
- We’d rather you finish reading knowing where you stand, whether you call us or not.
- See a doctor within 14 days of the crash. Miss the 14-day deadline and you lose Florida’s first layer of insurance money for good.
- You’ve got two years to file a lawsuit, not the four years many websites still say.
- The driver who hit you might not carry any injury insurance at all, and the policy that pays is often your own.
- The other side can’t use what you told the officer at the scene against you. You also don’t have to give the other driver’s insurance company a recorded interview.
- You can get the crash report yourself about ten days after the crash.
- Agencies and camera vendors erase road records, video and signal data on schedules measured in weeks. A lawyer sends the letters that stop the erasing.
- Andrew Pickett prosecuted cases in the same courthouse system where your case would be tried, and he takes cases to a jury.
- The crash report. Ready in about ten days. Locked to you, your lawyer and your insurer for the first 60 days.
- School zone camera video. Destroyed 90 days after the ticket from that day is finished.
- Road and signal records. Held by the state, and released to anyone who asks in writing.
- Your car. Repaired or sold for salvage within weeks, taking the damage pattern with it.
If you were just in a crash here, your car has probably already gone somewhere on a tow truck. Someone from an insurance company called and sounded friendly. Maybe you’re replaying what you said to the officer and wondering whether you hurt your own case.
Start with whether you have a claim at all. The decisions about hiring a lawyer come next. The rules and the statute citations sit further down, once you know whether you need them.
How Do I Know If I Have a Claim?
Most people ask whether they have a claim only after the other driver’s insurance company has hinted at an answer. Florida decides whether you have a claim with three tests, and you can check the first two yourself.
Was someone else more at fault than you? Florida stops paying entirely once your share of the blame passes fifty percent. If you’re forty percent at fault, you still recover, reduced by forty percent. When the insurance company tells you early that most of the blame was yours, they’re giving you an opinion, not a finding.
Is your injury permanent? You reach money beyond the first layer of insurance only with a permanent injury. Florida counts four kinds of permanent injury: lasting loss of an important bodily function, an injury a doctor calls permanent to a reasonable degree of medical probability, serious permanent scarring, and death. Your doctor usually settles whether the injury is permanent in your first two months of treatment.
Is there money to reach? Florida doesn’t require drivers to carry coverage for the injuries they cause. When the driver who hit you carried no injury coverage, you collect from your own policy instead. Insurers call a policy that covers an uninsured driver’s damage uninsured motorist coverage.
You can answer the fault question and the coverage question from paperwork you can gather today. Only a doctor can tell you whether your injury is permanent.
take action / Step 3 We fight for you. Same block used on /melbourne/ and /titusville/.]
Run the Arithmetic Before You Hire Anyone for a Small Claim
Some people settle a car accident claim without a lawyer and do fine. Here’s the arithmetic on a small claim.
Say you went to the emergency room, had eight weeks of physical therapy, missed three weeks of work, and recovered fully. You run up about $9,000 in bills and lose about $2,400 in wages, with no permanent injury.
People call Florida a no-fault state because your own car insurance pays the first medical bills whatever caused the crash. Your own insurer pays 80 percent of medical bills and 60 percent of lost wages. If a qualifying provider records an emergency medical condition, your ceiling goes from $2,500 to $10,000.
With an emergency medical condition on record, your insurer pays $7,200 of your $9,000 in bills and $1,440 of your $2,400 in wages. The $8,640 total sits under the $10,000 no-fault ceiling. You claim the remaining $1,800 in bills and $960 in wages from the driver who caused the crash. You can’t claim pain and suffering without a permanent injury.
You can handle a small claim yourself if your injury stays temporary, the driver who hit you carried insurance, fault stays undisputed, and the insurer pays what the policy owes.
A lawyer can request an insurance file, a police record and a medical opinion in week two, and an injured person acting alone usually can’t.
Your doctor may not have written the permanence finding into your record yet. Somebody has to request the other driver’s coverage limit in writing before you know it. The other driver’s insurer will ask you to sit for a recorded interview, and fault usually turns into a dispute after you give it.
A small claim is still your money, so spend an afternoon on it rather than two years. Someone who doesn’t handle accident claims for a living can’t check injury, insurance, fault and payment the way a lawyer can. The fine print only shows up in the files. Andrew Pickett Law handles small cases alongside large ones, and the case review is free. You’re not signing up for anything by asking. You can find out in a half-hour call whether fault, coverage, permanence or the insurer is a problem in your case. Even if you never call back, you hang up with a clearer picture of your own options.
A Car Accident Lawyer’s Fee Comes Out of the Recovery, Never Your Pocket
Andrew Pickett Law takes its fee only out of what we recover for you. We take a minority percentage of any recovery, and we charge no fee at all if we recover nothing. Lawyers call a fee paid only out of a recovery a contingency fee. You’ll never write us a check to get started, and you’ll never see an hourly bill.
Florida law caps the percentage a law firm can charge, so no firm sets its own ceiling. We back the fee cap Florida sets with a commitment of our own. We work your case to its maximum value, and we spend money building that value long before a settlement arrives. We pay the filing fees, we order the medical records, and we hire the experts, and you’ll receive no bill while you’re still healing.
Ask any firm you talk to, including us, who pays the advanced costs if you lose. Different firms give different answers, so get the answer in writing before you sign anything.
What Changes If An Accident Victim Goes Back To Work Right Away?
You don’t close your injury claim by going back to work, and you don’t settle the permanence question either. You change the wage part of your claim by going back, and you leave the injury part alone.
Your claim has a wage part and an injury part. Your wage claim shrinks, because your insurer pays 60 percent of the wages you actually lose, and you can’t claim wages you never lost. Your doctor decides whether your injury counts as permanent, and your attendance at work doesn’t enter into it.
An insurer may argue that a quick return to work shows a minor injury, and your medical record answers the argument. Tell your doctor what you can and can’t do at work, and make sure the doctor writes it down. Ask for a note about restricted duty, because a restricted-duty note explains why you went back.
Plenty of people go back because they can’t afford to stay off work. Give money as the reason if anyone asks why you returned, and give your doctor the same answer.
A Former Prosecutor Who’s Stood in Your Courtroom
Andrew spent years as a prosecutor in the Eighteenth Judicial Circuit before he represented injured people. He’s stood in the courtroom your case would be tried in, and he knows how the other side prepares. He trained at the Trial Lawyers College, and he tries cases to verdict. An insurance company prices a file differently when the lawyer across from it has taken cases to a jury.
Clients tell us the same thing in their reviews: they always knew what was happening in their own case. We’ll tell you what the next step is and roughly when it happens. If something changes, we’ll tell you about the change too.
Your First Call Is a Conversation, Not a Commitment
A first call is a conversation, not a commitment. You describe the crash, and someone tells you whether you have a claim and what a next step would look like. You’ll pay nothing for the call or the review.
Bring what you have: the crash report number, the name of your own insurer, and the names of anyone who has treated you. You can call with no paperwork at all.
If Andrew Pickett Law takes your case, the fee comes out of a recovery. You’ll pay nothing out of pocket while the case runs. If the honest answer is that you don’t need a lawyer, you’ll get that answer too.
The Two Deadlines That Can End Your Claim
Two clocks started the moment your crash happened. Neither one stops while you rest or wait for a phone call back.
See a doctor within 14 days
See a doctor within 14 days of the crash, even if you feel mostly fine. Florida pays the first layer of insurance money only to people who got care inside that window.1 Missing it does not shrink the money. It erases it. A hospital visit on the day of the crash counts. So does urgent care, and so does your regular doctor.
File a lawsuit within two years
You have two years to file a lawsuit over a car crash here.2 The deadline used to be four years. The law changed in March 2023, and many websites still show the old number. Anyone trusting the four-year figure is planning around two years that no longer exist. When a crash takes a life, the two years run from the date of death instead.
A government vehicle changes the timing again. Suppose a city truck hit you, or a broken signal played a part. Before you can sue a government agency, you must send it a formal written notice of your claim and give it time to answer. The law calls that step a pre-suit notice.3 A claim against a government agency runs on a longer clock than a claim against another driver: four years to file the lawsuit, and three years to deliver the written notice. What the clock does not do is stop. The agency’s silence does not extend your time, and after six months without an answer the law treats the claim as denied so you can sue.
Who Pays Your Medical Bills After a Crash
Your own car insurance pays your first medical bills, no matter who caused the crash. Florida is called a no-fault state for that reason. The coverage doing the work is called personal injury protection, or PIP. It pays 80 percent of your medical bills and 60 percent of your lost wages, up to $10,000.1
A smaller limit hides inside that $10,000. Unless a doctor decides you had an emergency medical condition, PIP stops paying at $2,500.4 Only certain providers can make that call: a physician, an osteopath, a dentist, a physician assistant, or an advanced practice registered nurse. The decision is a note in your records, not a feeling about how bad the crash looked. Ask your doctor directly whether that note has been made.
Money past PIP comes from the at-fault driver, and Florida only opens that door for a permanent injury. Florida counts four kinds of permanent injury: a lasting loss of an important bodily function, a permanent injury shown to a reasonable degree of medical probability, serious permanent scarring or disfigurement, and death.5 Your medical records from the first two months usually settle this question, long before anyone feels ready to think about it.
Fault still matters above the PIP layer, and it now comes with a cliff. A person found more than 50 percent responsible for their own harm recovers nothing.6 Suppose you were rear-ended on US 1 in the afternoon commute. You mentioned to the officer that you had glanced at your phone a moment earlier. That does not make the crash your fault. It is still the first thing the other insurance company builds on, and the recorded interview they asked for in week one is where the building starts.
What Happens If the Driver Who Hit You Has No Insurance
The driver who hit you may legally carry nothing that pays for your injuries. Florida requires drivers to insure damage to other people’s property and to carry PIP for themselves. It does not require bodily injury coverage, the coverage that would pay for the harm done to you.7 Finding that out surprises almost everyone.
Your own policy usually holds the answer. Coverage called uninsured motorist coverage, or UM, steps in and pays what the missing coverage would have paid.
A hit-and-run works the same way. When the other driver is never found, the claim runs through your own UM coverage. Report the crash quickly, because most policies set their own notice deadlines. Save anything that might identify the vehicle, from a doorbell recording to debris left in the road.
A different rule applies when the other driver has coverage but not enough. Before you settle with that driver’s insurer, you have to tell your own carrier: written notice of the proposed settlement, sent by certified or registered mail, and then 30 days for your carrier to respond.8 Settling without that notice can cost you the underinsured motorist claim, which is usually the largest number on the table.
What You Actually Take Home From a Settlement
Hospital bills overstate what a case pays. A jury now hears what was actually paid for your care, not what was billed.9 The gap between those two numbers is often large. Care arranged through a letter of protection, where a doctor treats you now and collects from your settlement later, has to be disclosed too. That gap explains why an early offer and a final result can look so different.
A hospital can also claim part of your settlement before you see it. Lawyers call that claim a lien. Florida has no statewide hospital lien, and most counties here have none at all. Brevard County is one of the few that does. A hospital that files its claim with the Clerk of the Circuit Court within ten days of your discharge holds a lien on your recovery.10 A release signed without settling that lien creates a problem for whoever took the money. Checking the Clerk’s records first costs almost nothing.
The Titusville personal injury page covers liens and the rest of the money picture.
The Proof of What Happened Is Already Disappearing
Right now, while you are healing, the proof of what happened to you is on a schedule to be erased. Nobody is doing anything wrong. Cameras record over old video, and record keepers purge files on a timetable set long before your crash. The agencies and companies holding those records have no duty to keep them for you, and no way of knowing you exist.
Proof is the part of a car accident claim people lose without ever learning they lost it. Below is what exists right now, who holds it, and how long you have.
Only certain people can get your crash report for the first 60 days
The place your crash happened decides who wrote your report. A crash inside the Titusville city limits usually belongs to Titusville Police. Outside the city limits it belongs to the Brevard County Sheriff’s Office. On I-95 and the state highways it belongs to the Florida Highway Patrol, whose Brevard station sits in Cocoa.
Reports come available about ten days after a crash. For the first 60 days, only the people involved, their lawyers and their insurers can get one. You will need to sign a statement confirming you are one of those people, and pay a small fee.11
Some crashes never produce a report at all, because the duty to report has a dollar floor. A driver must report a crash with apparent property damage of at least $2,000. That floor used to be $500.12 Any page still quoting $500 is working from an old copy of the law. If no officer came to your crash, you can file a driver report yourself, and you should. A missing report becomes an argument later about whether the crash happened the way you say.
A school zone camera may have recorded your crash, and the clock is running
Titusville runs speed cameras in ten school zones, from Titusville High on Terrier Trail to the elementary schools along Knox McRae Drive and Garden Street. The city ordinance behind those cameras allows the video to be used for deciding civil liability, not just for speeding tickets.13 The same ordinance orders the video destroyed within 90 days after the recorded event is finally resolved. A crash inside one of those zones may sit on a pole camera right now. Nobody saves that video for you, so a written request has to reach the city and its camera vendor within weeks.
Telling the wrong government is the same as telling nobody
Southbound US 1 through downtown was resurfaced from the FEC railway bridge to Grace Street between early 2025 and early 2026. The work upgraded the traffic signals at Garden Street, Main Street, Julia Street, South Street and Grace Street, rebuilt the crosswalks and curb ramps to current accessibility standards, and added sidewalk connections to the bus stops.14 Records from that project still exist. They include the plans showing how lanes were rerouted during construction, and the timing sheets for each signal. FDOT releases project documents on request. A street photograph taken before 2026 no longer shows the markings, ramps or signal equipment a jury will see.
The government that owns the road decides where your complaint about it has to go. The City of Titusville publishes a list of streets it does not maintain. I-95, US 1, SR 50, SR 405, SR 406 and SR 407 belong to FDOT. Barna Avenue, Carpenter Road, Dairy Road and Parrish Road are among those belonging to Brevard County.15 A claim about a broken signal or a dark crosswalk starts with the pre-suit notice described earlier. A notice sent to the wrong government is a notice nobody ever gave.
Your car is proof, and it costs you money every day it sits
Brevard County caps what a towing company may charge for a tow you did not arrange.16 Storage runs in 24-hour blocks rather than calendar days. Many people have heard that a towing company must release a vehicle within an hour of being asked. That rule is written to exclude cars towed from a crash scene, so storage charges build while you and the insurance company sort things out. Get your belongings out early. Photograph the car from every side before it is repaired or sold for salvage, because the damage pattern is proof that repairs erase.
When Someone Besides the Driver Is Responsible
A bar or restaurant that served a drunk driver is usually not on the hook. Florida law makes two narrow exceptions. The first covers knowingly serving alcohol to someone under 21. The second covers knowingly serving a person who is habitually addicted to alcohol.17 Proving either one depends on records the business keeps and does not offer, from sales receipts to training logs. Those records follow the same rule as everything else on this page. They exist today, and somebody has to ask for them.
Frequently Asked Questions About Car Accident Claims
Why did my $10,000 of no-fault coverage stop at $2,500?
No qualifying provider decided you had an emergency medical condition. Only a physician, an osteopath, a dentist, a physician assistant or an advanced practice registered nurse can make that decision. Without it, PIP caps at $2,500 no matter what your care cost.4 Where the facts support it, ask your treating doctor whether that decision belongs in your records.
Did Florida get rid of no-fault insurance?
Florida kept it. Lawmakers have filed bills to repeal PIP more than once, and each one died in committee, most recently in 2025 and again in 2026. The law is still in force.1 Confident-looking websites still say otherwise, including some that look generated rather than written.
The other driver has no insurance. Is my claim over?
Your claim usually survives. The recovery moves to the uninsured motorist coverage on your own policy. Florida does not require drivers to carry bodily injury coverage, so this happens often.7 If that driver has some coverage but not enough, tell your own carrier by certified or registered mail before you settle, and give it 30 days to respond.8
Should I give the other driver’s insurance company a recorded interview?
You do not have to, and doing it early rarely helps you. The recording exists to find something usable for the more-than-half-at-fault argument described above. Your own insurance company is a different matter, because your policy generally requires you to cooperate with them.
What if no police officer came to the scene?
File a driver report yourself. Photograph the cars and the scene before anything moves. Get the other driver’s insurance details in writing rather than trusting memory. A crash with no report invites an argument later that things happened differently than you say, and the report you file closes that door while the details are fresh.
Can a hospital take part of my settlement?
A Brevard County hospital can, if it filed its claim with the Clerk of the Circuit Court within ten days of your discharge.10 Most Florida counties have no hospital lien at all, so advice written for the rest of the state misses this. Search the Clerk’s records before you sign a release. Treat an unsettled lien as a number still to be negotiated, not a bill that went away.
Four Things People Get Wrong About Car Accident Claims Here
“I have four years to file.” You have two years for any crash after March 24, 2023. The four-year figure still circulating was retired by the 2023 change in the law.2
“No-fault means nobody is at fault.” No-fault only describes which insurance pays first. Fault still decides everything beyond PIP, and a person found more than half responsible recovers nothing.6
“The at-fault driver’s insurance will cover my injuries.” Only if that driver bought bodily injury coverage, which Florida does not require. The policy that ends up paying is often your own.7
“My case is worth what the bills say.” A jury hears what was actually paid, not what was billed, and the gap between those numbers is often large.9
References
- Fla. Stat. § 627.736 — personal injury protection; 14-day treatment requirement; 80% medical and 60% wage benefits within the $10,000 limit.
- Fla. Stat. § 95.11(5)(a) — two-year limitations period for negligence, as amended by ch. 2023-15.
- Fla. Stat. § 768.28 — waiver of sovereign immunity; pre-suit notice and damages caps.
- Fla. Stat. § 627.736(1)(a)4 — the $2,500 limit absent an emergency medical condition determination, and the providers who may make it.
- Fla. Stat. § 627.737(2) — permanent injury threshold for non-economic damages.
- Fla. Stat. § 768.81(6) — modified comparative negligence; recovery barred above 50% fault.
- Fla. Stat. § 324.022 — financial responsibility; $10,000 property damage liability, no bodily injury liability required.
- Fla. Stat. § 627.727(6)(a) — certified or registered mail; 30 days for the underinsured motorist carrier to authorize settlement or retain subrogation rights.
- Fla. Stat. § 768.0427 — evidence of medical damages; amounts paid rather than billed; letter of protection disclosure.
- Brevard County Code §§ 54-66 to 54-71 — liens for hospital care; ten-day filing with the Clerk of the Circuit Court.
- Fla. Stat. § 316.066(2) — crash report confidentiality for 60 days; § 316.066(2)(d) — photographic identification and written sworn statement. Fees are set elsewhere: $10 per report from FLHSMV under § 321.23; local agencies charge their own duplication fee under ch. 119. Section 316.066(4) makes statements to law enforcement inadmissible in a civil trial.
- Fla. Stat. § 316.065(1) (2026 Florida Statutes) — $2,000 property damage reporting threshold. Cite the 2026 compilation explicitly: the 2025 compilation still reads $500. Verified 29 Aug 2026.
- Titusville Code of Ordinances §§ 20-70 to 20-80 (Ord. No. 16-2025) — school zone speed detection; § 20-75 designated zones; § 20-77 permitted use for civil liability and 90-day destruction requirement.
- FDOT project 448800-1 — southbound US 1, FEC Railway Bridge to Grace Street, Titusville; work type resurfacing, with signal upgrades, crosswalk and curb ramp reconstruction and new sidewalk connections. FDOT’s project page is archived as completed (checked 30 Aug 2026).
- City of Titusville — streets not maintained by the City.
- Brevard County Code § 106-5 and Resolution 2008-150 — maximum non-consent towing and storage rates.
- Fla. Stat. § 768.125 — liability for injury caused by intoxication; the two exceptions.
Other Case Types We Handle
- Truck Accident
- Motorcycle Accident
- Uber & Lyft Accident
- Pedestrian Accident
- Bicycle Accident
- Scooter Accident
- Golf Cart Accident
- Boating Accident
- Slip and Fall
- Premises Liability
- Airbnb and Vacation Rental
- Dog Bite
- Sexual Abuse
- Workers’ Compensation
- Wrongful Death
Areas and Zip Codes Served From Our Titusville Office
- Titusville — 32780 and 32796
- Mims and Scottsmoor — 32754
- North Brevard County
Free Case Evaluation
Please describe what happened. We will review your case for free and work to secure the highest legal compensation possible.
5000+ Cases Reviewed
Sebastian Martinez
$200,000 Verdict
"Our family is flat out impressed with the Andrew Pickett Law firm technical mastery, they never wavered with kind direction as our recovery prolonged during the COVID-19, and they delivered the maximum settlement possible."
how the claim process works
Step 2
We take action
Our dedicated team gets to work investigating your claim.
Step 3
We fight for you
If we take on the case, our team fights to get you the maximum compensation legally possible.
Free Case Evaluation
Please describe what happened. We will review your case for free and work to secure the highest legal compensation possible.
5000+ Cases Reviewed
Beatrice Maxime
$1,000,000 Verdict
"I am so very grateful to have had this firm represent me. I was in a car accident a few years ago, but the car insurance company of the person who totaled my car would not replace my car, nor pay for my medical bills. We ended up going to court and because of Mr. Pickett, we won the case. Thank you so much for all you did for us!!!!"
Meet Andrew Pickett
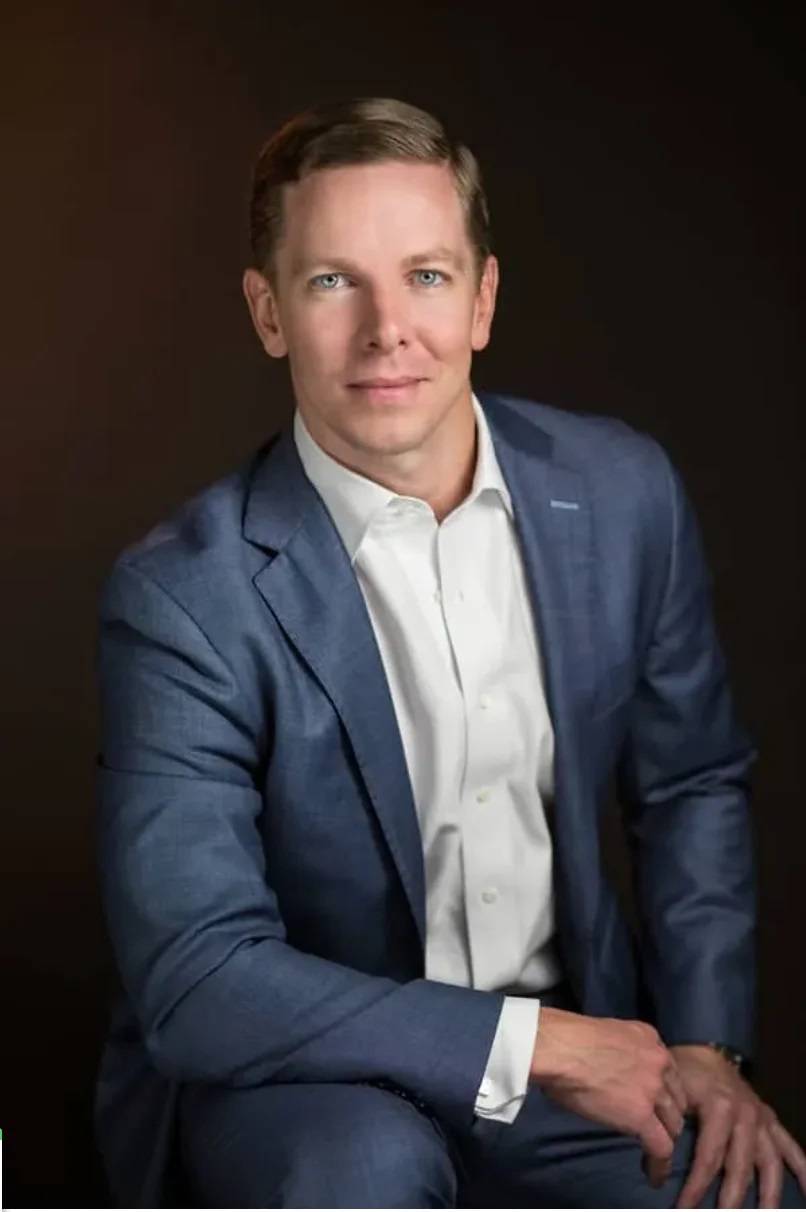
Dealing with the murky policies of insurance companies designed to confuse and prevent you from receiving compensation is our expertise.
15+ years experience as a personal injury attorney.
Specialized in battling insurance companies.
95% settlement rate for clients.
Handled 500+ personal injury cases.
Collected more than $38 million for clients.
500+ people have chosen Andrew as their attorney.
520+ Satisfied Clients
Our latest reviews on Google

Jennifer Cleveland
1 month ago
Lauren and her team are the best! Thank you for all the help, I 10/10 recommended them!

Ivanova Rodriguez
1 month ago
Great experience, kindness people

andrew rafidi
1 month ago
Project Backpack was a major success! Wonderful community outreach event! Emma Vinson is incredibly kind and helpful!

michele stanevich
1 month ago
What a wonderful event. Very well organized. He introduced himself to everyone. I will keep him in mind if and when I need a lawyer.

Lisa & Andrew Arnabat
1 month ago
Our team (attorney Tiffany Whitehouse, paralegals Vonda and Lindsey, our legal assistant Lauren, and Caroline) at Andrew Pickett Law has been absolutely amazing. They have been communicative from start to finish and have gone above and beyond in all aspects. They treated us like people, not like another number. Thank you for all of your help & guidance throughout what would have been an otherwise overwhelming and confusing process.

Thomas Preston
2 months ago
Andrew Pickett law for is a real good law and I will recommend him to need a real good lawyer.Thank you very much from my case.My name is Thomas Preston.Thank you

Close Family
3 months ago
Andrew Pickett and his team were very professional and supportave throughout my whole case. They took care of all the bills and successfully negotiated with the insurance companies. They were able to get 850,000 towards all the medical bills. I would definitelly recommend them.

Orestes Olmo
3 months ago
(Translated by Google) Excellent service. I was recommended by my daughter-in-law, and the beginning has been wonderful. They asked all the necessary questions and were incredibly quick at the start of the process. I am very grateful for their attention. (Original) Excelente trato ,fui recomendado por mi nuera y la verdad el inicio a sido maravilloso, hicieron las preguntas necesarias y una rapidez increíble en el comienzo del proceso , les agradezco mucho esta atención

Caitlin Cheatham
3 months ago
Amazing experience, they got me the best settlement I could’ve asked for. Always responded quickly and kept me in the loop! Highly recommend

Heidi Bushing
3 months ago
The team at Andrew Pickett is amazing. They helped me with two accidents and have been very attentive and communicative.

pebbs jai
3 months ago
I highly recommend this law office. Special thank you to Allison W. for answering all my questions and concerns. All staff were very helpful, professional and pleasant. They also give back to the community so if you are looking for a well knowledgeable law firm this is it!! Mr Andrew Pickett I appreciate you.

Krissy Green
3 months ago
Thank you all for your support I appreciate so much you guys are awesome

Stephanie Mortier
3 months ago
I absolutely love this law firm , down to the absolute best communication, and the follow up calls with details . Thank you guys !

Kimmy Ware-Simmons
4 months ago
A special thanks to this wonderful team! I’ve been truly blessed to be represented by Andrew Pickett Law. All my questions have been attentively addressed and explained perfectly in a way I am fully able to understand. This Lawfirm treats everyone with respect and like family. 10/10 review and definitely recommend!
Stephanie Mortier
4 months ago
Thank you , she was very helpful and friendly .

Steve Ryland
4 months ago
Andrew and his team provided outstanding legal representation with a high level of professionalism, responsiveness, and attention to detail. He communicated clearly throughout the process and delivered a result we were very satisfied with. I truly appreciate his expertise and would highly recommend him to anyone in need of strong, reliable legal counsel.

christian leon
4 months ago
Working with Tiffany Whitehouse, Vonda, and Lauren at Andrew Pickett Law Firm was an amazing experience for me. They were really professional, attentive, and committed to my case from beginning to end. Their diligence and genuine concern for achieving the greatest result for me were what truly stood out. I genuinely felt like I was in good hands the entire time because of their dedication and teamwork, which made a difficult situation much easier to face. I got the best outcomes I could have imagined because of their hard work and knowledge. I am incredibly appreciative and would heartily suggest their team to anyone in need of legal assistance.

Erin Mclachlan
4 months ago
My experience is based on 2 settlements so far, still pending another case and 1 of the already settled cases M&M took but didn't want to keep after stringing me along for 4 months. So just choose Andrew Pickett Law, don't waste time with another injury attorney. Tiffany Whitehouse is great, she was confident in my cases, kept me informed and very accommodating. We didn't even have to go to court for those 2 cases. And because I had already trusted them with 2 cases, I also gave them a third case which settled quickly. My only regret, I just wish I had known about them sooner. Thanks for everything! I have already recommended my friends and clients and will continue.

Carlos Mangual
4 months ago
Tiffany Whitehouse has been a tremendous help to me through out my whole process majorly because of her communication she’s always one phone call or text away and really gives me comfort to have any of my questions or worries answered so quickly

Hannah Dorris
4 months ago
If I could give more than 5 stars I would. I cannot say enough amazing things about Tiffany Whitehouse and her entire team. From the very beginning, I felt genuinely cared for, supported, and prioritized throughout my entire experience. Tiffany is an absolute powerhouse her knowledge, confidence, and attention to detail truly set her apart from any attorney I’ve ever worked with. She knows her craft inside and out, and you can feel that level of expertise in every interaction. What really stood out to me was how responsive and efficient everyone was. Communication was always clear and timely, and I was never left wondering about the status of my case. Tiffany and her paralegal, Vonda, worked seamlessly together and made everything feel organized and stress-free. Vonda was incredibly kind, attentive, and always made sure I had what I needed. They both went above and beyond in ways that made a stressful situation feel manageable. I also want to recognize the admin team, especially Lauren and Hailey. They were so welcoming, helpful, and professional every time I interacted with them. It’s clear that this entire office operates with a high level of care, compassion, and dedication to their clients. Another thing that truly stood out to me was how thorough and patient everyone was when answering my questions. No matter how many I had, they took the time to explain everything in detail and made sure I fully understood even if it took 20 minutes. That level of patience and dedication meant so much and made me feel confident every step of the way. What meant the most to me is that they didn’t treat me like just another case they truly cared about me as a person. They checked in regularly, made sure I felt supported, and consistently went the extra mile. That kind of genuine compassion is rare to find. If you’re looking for a legal team that is not only highly skilled but also truly invested in you, I wholeheartedly recommend Andrew Pickett Law. They exceeded all of my expectations and I am beyond grateful for everything they’ve done for me. Thank you all SO incredibly much!