Titusville Workers’ Compensation Lawyer

Andrew Pickett Law is a top Titusville workers’ compensation law firm that handles workplace injury cases throughout Titusville and North Brevard County for injured workers who need help getting medical treatment and financial recovery. Clients say in reviews that they were never left guessing, which matters while an insurance company decides your claim and no paycheck is coming.
520+ Google reviews
Free Case Evaluation
*By submitting this form, you agree to our disclaimer.
What You Need To Know
- A work injury claim has more moving parts than a form and a clinic visit, and the insurer decides most of the parts in the first month. A lawyer who works comp claims every day keeps the moving parts from being decided against you.
- You’re welcome to take what’s here and run the claim yourself. We’d rather hand you the rules than leave you guessing.
- Tell your employer about the injury within 30 days. A late report ends most claims here, however real the injury is.
- You collect medical care and part of your lost wages from workers’ comp. Comp won’t pay a dollar for what the injury put you through.
- You don’t lose benefits for being careless. The more-than-half-at-fault rule belongs to lawsuits, not to workers’ comp.
- Your employer’s insurance company picks your doctor. You can demand a different doctor once per claim in writing, and if nobody answers within five days, you pick.
- You get two years to file, counted from the day you knew your injury came from work. A worn-out shoulder or a bad back may not be as late as it looks.
- A state comp judge decides your case in the county where you were hurt. Andrew Pickett prosecuted in the same Brevard circuit and tries injury cases to verdict.
- The federal badge. A NASA civil servant is a federal employee. The injury claim runs under the federal comp law, FECA, instead of anything on this page. The filing goes to the Office of Workers’ Compensation Programs through its online system, ECOMP. The deadline to file is three years rather than two.5
- The contractor badge. A contractor employee standing beside a NASA civil servant holds a Florida claim, and the Florida rules apply in full. The badge may say SpaceX, Blue Origin, Jacobs, Amentum, L3Harris, Boeing, or United Launch Alliance, and that worker still files a Florida claim.
- The fence line. Federal land does not make a claim federal. Federal law extends state workers’ compensation law onto federal property as if the land belonged to the state. A contractor hurt inside the gate reports under the 30-day rule and files a state claim.6
- The Defense Base Act. Aerospace workers ask about this third law because the name circulates at work. It covers contractor work outside the continental United States, so it has no application to an injury at Kennedy Space Center or Cape Canaveral.7
If you got hurt on the job here, the hard part started before any legal question came up. Telling your boss feels risky, because you need this job and you do not want to be the employee with a claim on file. Someone has probably already sent you to a clinic you did not pick. Under both worries sits money. You have to live on something while your body decides how bad this is.
Start with the report, because a late report ends most claims here. Retaliation, whether you need a lawyer at all, and the fee come next. The benefit rules, the doctor rules and the statute citations sit further down.
Report It in Writing Within 30 Days
Tell your employer you got hurt at work before you do anything else. Report late and Florida law kills your claim in nearly every case, however badly you’re hurt.
You’ve got 30 days. Put the report in writing, keep a copy, and don’t rely on having mentioned it to a supervisor in a hallway.
Write down the date, the time, what you were doing and who saw it happen. A written report on day three beats a perfect memory on day ninety.
You may also be less late than you think. A worn-out shoulder or a bad back has its own starting date, and the clock on a repetitive injury runs from the day you knew the work caused it.
Your Employer Can’t Fire You for Reporting
Most people wait for a reason that has nothing to do with paperwork. You need the job, and you don’t want to be the employee with a claim on file.
Florida bans retaliation for filing a comp claim by name, and a firing that follows a report becomes a separate claim of its own. An employer who fires you for reporting has handed you a second case.
Reporting protects the job in a plainer way too. A claim on file is what makes a light-duty assignment, a doctor’s restriction and a paycheck substitute enforceable.
Report the injury in writing and keep working if you can. Nothing about a written report requires you to stop showing up.
A Comp Claim That’s Running Right Doesn’t Need Us
Plenty of comp claims run fine without a lawyer. You report on time, the carrier accepts the claim, the clinic treats you, the checks arrive, and you go back to work. Nobody needs to take a percentage of a claim that runs itself.
A claim turns adversarial at moments you can recognize. The carrier denies a benefit. Fourteen days pass with no check and no denial letter. The company doctor says you’ve reached maximum improvement while you still can’t lift your arm.
Call us when a denial, a missed check or a premature discharge shows up, and call us before you sign anything that settles the claim. A comp settlement closes your medical care as well as the money, and a closed claim stays closed.
The call costs nothing. If your claim is running the way it should, we’ll tell you and you can carry on without us.
What a Workers’ Comp Lawyer Costs
The fee in a comp case is set by comp’s own law, so none of the numbers on our other pages apply here. Our other Titusville pages describe the sliding percentage caps the Florida Bar sets for ordinary injury lawsuits. Chapter 440 writes its own schedule instead. The fee starts at 20 percent of the first $5,000 of benefits the lawyer gets you, then 15 percent of the next $5,000. After that it is 10 percent of the rest of the benefits due in the first ten years after the claim is filed, and 5 percent of anything secured after those ten years.22 So the last step down is about time, not size.
In 2016 the Florida Supreme Court held that the schedule cannot be applied as an unbendable rule.22 The schedule now works as a starting point, and a judge may adjust a fee that comes out unreasonable. We can tell you the schedule and a judge’s power to adjust it. No firm can quote you one flat number at the door.
You never write Andrew Pickett Law a check to get started, and you never see an hourly bill from us. If we get you nothing there is no fee. Where the money comes from depends on how the case ends. When the carrier denies a benefit and we win it back, Florida makes the carrier pay our fee on top of what you receive.22a When the case ends in a lump-sum settlement instead, the fee comes out of that settlement. We put the fee on the table at the first meeting, because the percentages are public and the arithmetic is short. Ask us which one your case looks like, and ask us to walk the schedule against the benefits you expect, before you sign anything. Ask any other firm you talk to for the same thing. We work your claim for everything it will pay, and we would rather you understand that number than take it on faith.
We Treat Telling You the Next Deadline as Part of the Job
Andrew spent years as a prosecutor in the Eighteenth Judicial Circuit before he represented injured people, and he has stood in the local courtrooms where the lawsuit half of a work injury gets tried. He trained at the Trial Lawyers College, and he tries injury cases to verdict. An insurance company prices a file differently when the lawyer across from it has taken cases to a jury.
Clients tell us the same thing in their reviews: they always knew what was happening in their own case. A comp claim runs on deadlines measured in days, and a worker out of work is waiting on other people’s decisions. We treat telling you which deadline comes next as part of the job, and we’ll call you when something changes.
Tell Us the Report Date and What the Carrier Has Done Since
A first call is a conversation, not a commitment. You describe the injury, the date you reported it and what the carrier has done since, and we’ll tell you which deadline is running and what the carrier owes you now.
Bring the date of the injury, the date you reported it, and the name of the clinic they sent you to. You can call with no paperwork at all.
If Andrew Pickett Law takes your claim, our fee follows the comp schedule rather than coming out of your pocket. If the claim doesn’t need a lawyer, we’ll tell you and you can keep running it yourself.
Reporting Late Ends Most Claims, However Real the Injury
Telling your employer that you got hurt at work matters more than anything else you do this month. If you report late, Florida law bars your claim in nearly every case, no matter how badly you are hurt.1 You have 30 days. Put the report in writing, so nobody can argue about the date later.1
The 30 days do not always start with an accident, because many work injuries have no accident at all. A shoulder wears out under years of overhead work, a back gives way slowly under lifting, and long exposure damages lungs. For an injury that builds over time, the clock starts at the first sign of trouble. The law looks for the point where the problem showed itself and could be tied to the job.1 Report when you first make that connection, even if the last shift you blame was years ago.
Florida law excuses a late report in four situations. The employer already knew about the injury. Only a doctor could connect the injury to the job. The employer never posted the required notice telling workers to report. Something exceptional stopped the report.1 The first two exceptions do real work. A supervisor who watched you fall has knowledge that no missed deadline erases. A repetitive injury that nobody could tie to work without a doctor starts its clock at that opinion. Treat the exceptions as a net under a report that is already late, never as a reason to wait.
Firing you for reporting is against the law by name
The fear that stops most reports is the fear of losing the job. Florida law makes it unlawful for an employer to fire, threaten, intimidate, or coerce a worker for filing a workers’ compensation claim.2 Trying to file one is protected the same way. A violation gives you a separate lawsuit against the employer, apart from the comp claim and decided in a different forum. Save every message and write down every conversation if you get treated differently after you report. A lawyer builds a retaliation case out of exactly that record.
take action / Step 3 We fight for you. Same block used on /melbourne/ and /titusville/.]
You May Not Be as Late as You Think
Plenty of injured workers read one sentence about a two-year deadline and decide they are finished. The deadline is real, and the start date is not the one most published material gives. Your two years run from when you knew, or should have known, that your injury came from your work.3
An accident is only the easy case. The machinist whose grip failed over ten years gets his two years from the day the connection became clear. So does the inspector whose breathing got worse across many seasons. No single shift on the floor starts that clock for them.
Payments push the deadline out again. Every wage check the insurance company pays, and every treatment it furnishes, gives you a fresh year from that last payment or treatment.3 A worker whose benefits ran for three years has not lost the claim at the two-year mark. The payments themselves kept the door open. Before you accept that you are too late, look up the date of the last benefit anyone paid you.
Some Employers Here Do Not Have to Carry This Insurance
Coverage here turns on headcount, and some Titusville employers do not have to carry it at all. A business outside construction must carry workers’ compensation once it has four or more employees. A construction employer must carry it with one. Agricultural employers are exempt at five or fewer regular workers.4
Someone hurt at a three-person shop may genuinely have nothing to file here. Being paid on a 1099 raises a second question, because the label on the paystub does not settle whether you are an employee. Check the headcount and your job classification before anything else in a small-business injury. They decide whether you are in this system at all.
A Badge at Kennedy Space Center Decides Which Law Covers You
A NASA civil servant and a contractor can be hurt on the same pad and hold claims in two different systems. The badge decides it, and getting that wrong costs a worker the deadline as well as the forum. Read the four positions below against your own employment before you count a single day.
Employment status decides which system you are in, and geography decides nothing. The belief that the fence line controls is the most common mistake in Space Coast work injuries. That mistake sends people to the wrong office with the wrong paperwork. If you are unsure which badge you hold for legal purposes, settle that question before you count any deadline.
The Titusville personal injury page covers the federal land rules for an ordinary injury lawsuit.
Being Careless Does Not Cost You a Dollar Here
The mistake you keep replaying does not reduce your benefits. Workers’ compensation is a no-fault system in the full sense of the phrase. A worker who tripped over his own bootlace collects the same benefits as the worker flattened by someone else’s forklift. The trade runs both ways, since you also collect without proving your employer did anything wrong.
If you have read another page on this site, you have met a harsher rule. In an injury lawsuit, a person found more than half responsible for an accident collects nothing at all. That rule governs negligence lawsuits and has no application to a workers’ compensation claim.8 Nobody will assign you a percentage of blame here, because this system keeps no such ledger.
Cause comes back into the case in one place: drugs and alcohol. A positive test after a workplace accident creates a legal presumption that the substance caused the injury. Refusing the test creates the same presumption a failed test does.9 The presumption gets harder to beat when the employer runs a certified drug-free workplace program. That is the opposite of what most people would guess. A worker facing a post-accident test result is facing the sharpest coverage fight this system has.
This System Never Pays for What the Injury Put You Through
Workers’ compensation pays for the medical care your injury needs. It replaces part of the wages you lose while you cannot earn them. The list ends there, because nothing is ever added for pain and suffering, at any level of severity, in any comp case, for anyone.1010a Our other Titusville pages describe money for the human cost of an injury. Every one of those pages is describing a lawsuit rather than a comp claim.
The pain-and-suffering money this system never pays changes more of your decisions than any other fact about your claim. A settlement that looks insulting against months of pain may be exactly what the law owes you. The law was never pricing the pain. Money for what an injury did to your life does exist after a workplace accident. It lives in a lawsuit against someone other than your employer, and that door opens when a third party helped cause your injury.
The Insurance Company Picks Your Doctor, Not You
The clinic you were sent to is not a mix-up. Your employer buys this coverage from an insurance company, called the carrier in every letter you are about to get. The carrier chooses and pays for your doctor.11 A visit you set up yourself, even to a doctor you have seen for years, is generally a bill the carrier will not pay. The rule surprises almost everyone, because in every other corner of medicine the patient picks.
Ask your employer for treatment first. If the employer fails to provide that first treatment within a reasonable time after a specific request, you may get that initial care yourself at the employer’s expense.12 The request is the key. A worker who goes straight to his own doctor eats the bill. A worker who asked, waited a reasonable time, and then went has moved that bill to the employer. Make the request in writing and keep a copy.
You also get to switch doctors once per claim, and you can do it without hiring anyone. Weigh that before you decide whether you need us at all.
Your Pay Stops Before the Benefit Checks Start
Rent does not wait for an insurance company, and the first weeks after a work injury are the ones that frighten people most. Wage checks in a comp claim run on published formulas, so you can work out most of what you will get with a calculator. The starting number is your average weekly wage, meaning the average of what you earned each week before you got hurt. Every example below uses a worker earning $900 a week, because arithmetic is easier to trust when you can follow it.
The carrier has 14 days to pay you or turn you down
The carrier owes you an answer inside two weeks. The clock starts once your employer knows of the injury. It runs where the injury puts you out of work right away and keeps you out for at least eight days. By day 14 the carrier must pay the first check or deny the claim.13 Silence past that day is not ordinary processing. A claim sitting unpaid and undenied after two weeks is a claim that needs pushing.
Nobody pays you for the first week unless you are out more than 21 days
The carrier sends you no wage check for the first seven days you miss. Medical care is different and is covered from day one, so do not put off seeing the authorised doctor.14 The lost week comes back to you only if your disability runs more than 21 days, and then you are paid from the first day of it.14 A short recovery costs you one unpaid week. Plan for that gap in your first month, because the system builds it in on purpose.
Two-thirds of your pay while you cannot work at all
While your authorized doctor says you cannot work at all, your check equals two-thirds of your average weekly wage. The benefit has a formal name, temporary total disability, and on the $900 example it pays $600 a week.15 A cap sits on top of every comp check, set at 100 percent of the statewide average weekly wage. The cap trims only the checks of higher earners.
Light duty for less money does not end the checks
Going back to work on restrictions changes the formula instead of ending it. The system starts from 80 percent of your old average wage. If you now earn less than that mark, it pays 80 percent of the gap.15 The benefit is called temporary partial disability. On the $900 example the mark is $720. A light-duty job paying $500 leaves a $220 gap and produces a check of $176 a week. Run your own numbers the same way, because a check that does not match the formula is a check to question.
The statute book says your checks stop years before they really do
Temporary checks end at a milestone your doctor declares, the point where no further recovery or lasting improvement can reasonably be expected. The milestone is called maximum medical improvement, MMI on the paperwork, and reaching it does not mean you are well.16 It means the temporary stage of the claim is over and a different benefit takes over.
The printed law still says the temporary checks stop at 104 weeks. The Florida Supreme Court held that limit unconstitutional in 2016 and revived the older 260-week limit, and the legislature has never corrected the text.17 A worker reading the statute comes away believing the checks end three years earlier than they can actually run. So does a worker reading a page copied from it.
The rating your doctor writes down converts straight into money
After MMI, a doctor gives your permanent impairment a percentage rating, and the rating turns into weeks of a smaller check. The impairment check pays 75 percent of your temporary total rate, or $450 a week on our example.18 The rating buys two weeks of that check per percentage point up to 10 percent. From 11 through 15 percent it buys three weeks per point, four from 16 through 20, and six above 20. A 6 percent rating on a $900 wage therefore pays $450 a week for 12 weeks, or $5,400 in all. Seeing the arithmetic in dollars is the fastest way to understand why the rating gets argued about.
Why the Checks Start and Then Stop
Checks that arrive for months and then stop are the most disorienting thing this system does. A stoppage usually traces to one of two rules, and neither rule means the claim is over.
The first rule lets the carrier pay you while it makes up its mind. For 120 days after benefits begin, the carrier may pay you while it decides whether it accepts the claim at all. A denial can therefore arrive after months of checks that felt like acceptance.19 The window runs against the carrier too. A carrier that fails to deny inside the 120 days gives up its right to contest that the injury is covered. The only exception is a fact a reasonable investigation could not have found. Write down the date of the first check and count, because a denial on day 130 is an argument you can win.
The second rule lets a carrier stop your checks over a preexisting condition you never knew you had. When an MRI or X-ray shows wear, arthritis, or an old injury, the carrier gets an argument for stopping. It must keep paying only while the accident stays more than half responsible for your need for care. The comparison is against all other causes combined.20 The standard is called major contributing cause. It is how workers in their fifties get cut off months into a claim on the strength of an imaging report. A cutoff built on that argument is a medical dispute, and a judge decides it rather than the carrier’s letter.
If They Say No, a Comp Judge Decides Your Case, Not a Jury
A denial is not the end of the road, and the road does not run through the courthouse our other pages describe. You do not file a comp claim in the circuit court, and no jury ever hears one. Disputes go to a state office called the Office of the Judges of Compensation Claims. An appointed judge who hears nothing but comp cases decides them.21 The paper that starts a dispute is called a petition for benefits.
The schedule after you file is fixed by law rather than by the insurance company. You get a settlement conference run by a neutral, called a mediation, within 130 days of the petition. The final hearing follows within 210 days.21 The hearing happens where you were hurt, because state law sets the final hearing in the county where the injury occurred. A comp judge hears a Titusville injury in Brevard County rather than wherever the carrier or the employer would prefer.
The state also staffs a free help line for injured workers with procedural questions. The Employee Assistance Office answers at 1-800-342-1741, and calling it costs nothing and commits you to nothing. Use it for the questions that are really about paperwork, and keep your own record of what you are told.
When Someone Besides Your Employer Caused Your Injury
Somebody other than your employer may owe you the money this system will not pay. Suing your employer is generally off the table, even when the employer was plainly careless. Coverage is the trade at the center of this system. The worker collects benefits without proving fault, and the employer gets immunity from injury lawsuits. The immunity gives way on one narrow showing, made by clear and convincing proof. The employer meant to injure, or hid a danger it knew was virtually certain to hurt a worker who could not have known.23 Cases clearing that bar are rare, so plan on the employer not being a defendant.
Everyone who is not your employer stays fully suable. The same injury can support a comp claim and a lawsuit at once, whenever a third party helped cause it. The lawsuit is where pain and suffering can finally be claimed.10 On a launch complex that pattern is common rather than exotic, because crews from many companies share one worksite. The party at fault may be another contractor’s crane crew, an equipment maker, or a driver who hit you on the road. A delivery driver rear-ended on US 1 during her route holds two claims. She has a comp claim through her employer and an injury case against the driver who hit her.
The carrier takes part of any third-party recovery before you see it, and almost nothing written about these lawsuits says so. The carrier holds a repayment right against what you win from the third party, a claim on the money called a lien. It stands to get back 100 percent of what it paid you, after its share of costs and fees.24 The repayment drops to a smaller share when the worker proves he recovered less than the full value of his damages. That reduction has a name, equitable distribution. Arguing it well is often the difference between a settlement that nets something and one that nets almost nothing.
A deadline sits under the third-party lawsuit too. If the worker has not sued the third party within one year, the carrier may bring the suit itself. If the carrier then lets a second year pass, the right comes back to the worker.24 A case left alone for a year can be filed by an insurance company whose interests are not yours. Decide about that lawsuit early rather than late, while the choice is still in your hands.
The hospital lien described elsewhere on this site never reaches a comp case. Our other Titusville pages explain that a Brevard County hospital can claim part of an injury settlement. The hospital does it by filing with the Clerk of Court soon after discharge. The county ordinance behind that lien leaves workers’ compensation out entirely. No Brevard hospital lien attaches to a comp claim or to comp benefits.25 The repayment to plan around on a workplace injury is the carrier’s lien described above.
If the Company Doctor Has Stopped Listening, You Can Replace Him Yourself
This system hands you one tool outright, and using it takes no lawyer, no filing fee, and no hearing. Once per claim you may demand a different doctor, and the demand has to be in writing.26 After your written request the carrier has five days to authorize a replacement who is not professionally connected to the doctor you are leaving. A carrier that misses the five days loses the choice, and you then select the doctor yourself.
Injured workers give this right away every week by asking for it on the phone. A spoken request starts no five-day clock and leaves no proof, while a dated letter or email does both. Write the request today, keep a copy, and mark day five on your calendar. Many injured workers use this change, land with a doctor they trust, and finish their claims without ever hiring anyone. That is the system working the way it was designed to work. We would rather tell you so than watch you spend the change badly.
The limit on the tool deserves respect, because the change is once per claim and a claim can run for years. Spending it in the first frustrating week leaves nothing for the moment that decides real money. So does spending it on a replacement no better than the first doctor. A surgery recommendation or an impairment rating turns on one doctor’s opinion. Save the change for that moment.
Frequently Asked Questions About Workers’ Comp Claims
Can I go to my own doctor for a work injury?
Your own doctor is generally off limits at the start of a claim. The insurance company chooses and authorizes the treating doctor, and care you arrange on your own goes unpaid.11 The rule has two openings. An employer that fails to provide your first treatment within a reasonable time after a specific request becomes responsible for that initial care if you get it yourself.12 The exception is about the start of the claim. Once care is authorised, going outside the system is on you. You can also demand a different doctor once per claim, in writing. If the carrier stays silent for five days, you pick the doctor yourself.26
My checks started and then stopped. Can the insurance company do that?
A stoppage is legal in two situations and contestable in both. Inside the first 120 days the carrier may pay while it investigates, and it may still deny. A carrier that misses the 120 days can no longer deny the claim, except on facts a reasonable investigation could not have found.19 Later stoppages usually argue that degeneration or an old condition now outweighs the accident. A comp judge decides that dispute on medical evidence rather than the carrier’s letter.20
The accident was partly my fault. Do I still have a claim?
Fault does not reduce workers’ comp benefits, and a claim survives being entirely your own fault.8 The exception involves intoxication. A positive drug or alcohol test after the accident creates a presumption against the claim. Refusing the test does the same, and the presumption is hard to overcome.9
Can I sue my employer instead of filing for comp?
The law almost never allows it. An employer carrying comp coverage is immune from injury lawsuits. The exception requires clear and convincing evidence of deliberate intent to injure. It also covers a concealed danger the employer knew was virtually certain to hurt someone.23 A lawsuit over the same injury usually targets a third party instead, meaning anyone other than your employer who helped cause it.10
Does workers’ comp pay for pain and suffering?
Workers’ compensation never pays for pain and suffering, no matter how severe the injury.10a Money for the human losses of a workplace injury exists only in a lawsuit against someone other than your employer. Where a third party helped cause the injury, the comp claim and that lawsuit run at the same time.
Does a small business have to carry workers’ comp?
Most Titusville employers must carry it, and the cutoffs are specific. The requirement starts at four or more employees outside construction and at one in construction. Agricultural employers are exempt at five or fewer regular workers.4 If your employer sits near a cutoff, check the headcount and your classification before anything else.
References
- Fla. Stat. § 440.185(1) — 30-day report of injury or initial manifestation; failure bars a petition, subject to four exceptions (employer actual knowledge; cause identifiable only by medical opinion; employer failure to post notice; exceptional circumstances).
- Fla. Stat. § 440.205 — prohibition on discharge, threat, intimidation, or coercion for a valid claim or attempt to claim; separately actionable.
- Fla. Stat. § 440.19(1)–(2) — petitions barred unless filed within 2 years after the employee knew or should have known the injury arose out of work in the course and scope of employment; payment of any indemnity benefit or the furnishing of remedial treatment, care or attendance tolls that period for 1 year from the date of the payment. The tolling does not apply to the issues of compensability, date of maximum medical improvement, or permanent impairment.
- Fla. Stat. § 440.02(20) — coverage thresholds: non-construction 4+ employees, construction 1+, agricultural exemption at 5 or fewer regular employees.
- 5 U.S.C. § 8122(a) — FECA claim filing (3 years; 30-day notice preserving exceptions); claims administered by the Office of Workers’ Compensation Programs via ECOMP.
- 40 U.S.C. § 3172(a) — state workers’ compensation law extended to federal land as if the premises were under the exclusive jurisdiction of the state.
- 42 U.S.C. § 1651(a) — Defense Base Act coverage limited to work outside the continental United States, on foreign bases, or in territories and possessions; no application to KSC or Cape Canaveral.
- Fla. Stat. § 768.81 — comparative fault; governs negligence actions only and has no application in a chapter 440 proceeding, where benefits do not turn on fault.
- Fla. Stat. § 440.09(3), (7)(b)–(c) — intoxication presumption from a positive test or refusal; with a certified drug-free workplace program the presumption is rebuttable only by evidence excluding every reasonable hypothesis, otherwise by clear and convincing evidence.
- Fla. Stat. § 440.39(1) — an injured employee may accept compensation benefits under chapter 440 and at the same time pursue an action at law against a third-party tortfeasor.
- Fla. Stat. §§ 440.11(1), 440.13, 440.15, 440.16 — chapter 440’s benefits are medical care, temporary and permanent disability and impairment, and death benefits; the chapter provides no non-economic damages, and § 440.11(1) makes these benefits the exclusive remedy against the employer.
- Fla. Stat. § 440.13(2)(a) — the employer furnishes and the carrier authorizes medically necessary treatment; unauthorized care is generally not compensable.
- Fla. Stat. § 440.13(2)(c) — employee-obtained initial treatment at the employer’s expense after a request and the employer’s failure to provide care within a reasonable time.
- Fla. Stat. § 440.20(2)(a) — first installment paid or claim denied by the 14th calendar day after the employer’s notice, where disability is immediate and continuous for 8 or more days.
- Fla. Stat. § 440.12(1) — no indemnity for the first 7 days of disability unless disability exceeds 21 days, then payable from day one.
- Fla. Stat. § 440.15(2), (4); § 440.12(2) — temporary total disability at 66⅔% of average weekly wage; temporary partial disability at 80% of the difference between 80% of the average weekly wage and actual earnings; weekly maximum at 100% of the statewide average weekly wage.
- Fla. Stat. § 440.02(12) — maximum medical improvement defined.
- Westphal v. City of St. Petersburg, 194 So. 3d 311 (Fla. 2016) — the 104-week limit in § 440.15(2)(a) held unconstitutional; the pre-1994 260-week limit revived. The statutory text still recites 104 weeks.
- Fla. Stat. § 440.15(3) — impairment income benefits at 75% of the temporary total rate; weeks per percentage point by band (1–10% = 2; 11–15% = 3; 16–20% = 4; 21%+ = 6).
- Fla. Stat. § 440.20(4) — pay-and-investigate; failure to deny within 120 days waives the right to contest compensability absent facts undiscoverable by reasonable investigation.
- Fla. Stat. § 440.09(1)(b) — major contributing cause: the work injury must be and remain more than 50% responsible as compared to all other causes combined.
- Fla. Stat. § 440.25(1), (4)(d) — petition procedure before the Office of the Judges of Compensation Claims; mediation within 130 days; final hearing within 210 days of the petition, held in the county where the injury occurred.
- Fla. Stat. § 440.34(1) — the fee schedule: 20% of the first $5,000 of benefits secured, 15% of the next $5,000, 10% of the remaining benefits to be provided during the first 10 years after the claim is filed, and 5% of benefits secured after 10 years; Castellanos v. Next Door Co., 192 So. 3d 431 (Fla. 2016) — the mandatory schedule struck as a due-process violation; now a rebuttable starting point.
- Fla. Stat. § 440.34(3)(b) — where the employer or carrier files a response denying benefits and the injured person’s attorney successfully prosecutes the petition, the claimant recovers an attorney’s fee from the carrier or employer; fees do not attach until 30 days after the carrier receives the petition. Cf. § 440.20(11)(c) — on a settlement, the claimant pays the fee.
- Fla. Stat. § 440.11(1) — exclusive remedy; exceptions for deliberate intent or conduct virtually certain to injure, concealed from an unaware worker, proven by clear and convincing evidence.
- Fla. Stat. § 440.39(2), (3)(a), (4) — carrier subrogation; 100% recovery after costs and fees unless the worker proves less-than-full-value recovery (equitable distribution); carrier may sue after 1 year of worker inaction; the right reverts after 2 years.
- Brevard County Code § 54-71 — workers’ compensation excluded from the hospital lien article.
- Fla. Stat. § 440.13(2)(f) — one-time change of physician: written request; 5 days for the carrier to authorize an unaffiliated alternative; on failure, the employee selects and the selection is authorized.
Other Case Types We Handle
- Car Accident
- Truck Accident
- Motorcycle Accident
- Uber & Lyft Accident
- Pedestrian Accident
- Bicycle Accident
- Scooter Accident
- Golf Cart Accident
- Boating Accident
- Slip and Fall
- Premises Liability
- Airbnb and Vacation Rental
- Dog Bite
- Sexual Abuse
- Wrongful Death
Areas and Zip Codes Served From Our Titusville Office
- Titusville — 32780 and 32796
- Mims and Scottsmoor — 32754
- North Brevard County
Our latest reviews on Google

Queen Jones
10 days ago
⭐⭐⭐⭐⭐ I highly recommend Andrew Pickett and his entire team! When I first started my case, I was frustrated and didn’t fully understand the legal process, and I initially gave them a one-star review. But Andrew and his team never gave up on me. They continued to stand by my side, worked extremely hard on my behalf, and stayed committed to getting my case resolved. What really stood out to me was their dedication and willingness to keep fighting for the best possible outcome. They handled my case professionally and worked hard to get it settled. I’m extremely grateful to Andrew Pickett and his entire team for everything they did for me. If you’re looking for a legal team that will stand beside you, work hard for you, and see your case through, I definitely recommend giving them a call. Thank you, Andrew Pickett and team, for all your hard work and dedication!

Kev Albaugh
19 days ago
After being in a serious car accident, I hired Andrew Pickett and his team in Melbourne to handle my case. From day one, Mr. Pickett treated me with genuine respect, compassion, and professionalism. He took the stress completely off my shoulders so I could focus on recovering. I would also like to recognize Lindsay, Jeremy, Vonda, and Caroline for always keeping me updated throughout the entire process and addressing any questions or concerns I may have had. Thanks to Andrews incredible expertise and relentless advocacy, he secured a phenomenal outcome that exceeded all of my expectations. If you are looking for an honest, hardworking personal injury attorney on the Space Coast who delivers real results, look no further than Andrew Pickett Law. They are the best in the business.

Robbi Sandkulla
21 days ago
When my fiancé was in a serious car accident, we were completely overwhelmed, but Andrew Pickett and his team were an absolute blessing. They stepped in immediately, handled every detail with the insurance companies, and kept us updated every step of the way. Seeing how much stress they lifted off his shoulders was a huge relief. Andrew fought hard and won an amazing outcome for his case. We are so incredibly grateful for this firm's dedication and highly recommend them!

Teresa Wyatt
1 month ago
The Team at Andrew Pickett has been great, so far. Extremely quick, and thorough. Wasted no time, in getting my case started.

Alondra “Alo” Ruiz
1 month ago
Very friendly and helpful. Love that they give back to the community.

Angela Oravits
1 month ago
We truley appreciate the kindness and helping us and many with a back pack. It was great to meet Andrew and Thank him for his kindness.

Jae is bae
1 month ago
That was so sweet of them, giving out free backpacks and supplies for the kids and making it easier for the parents to come up and just grab the backpacks and go to get home to their children. Love this event for people. I hope to see them next year as well.

K SN
1 month ago
⭐⭐⭐⭐⭐ I cannot say enough good things about my experience with Phindile at Andrew Pickett Law. From the moment she answered the phone, she was kind, compassionate, and truly listened to everything I had to say. After spending almost 16 months with another law firm where I felt completely ghosted and struggled with a lack of communication, I was feeling frustrated and unheard. Phindile spent nearly an hour on the phone with me, patiently listening to my concerns, answering my questions, and walking me through the process. She made me feel like my case actually mattered. In that one phone call, I received more communication, care, and reassurance than I had during my entire 16 months with my previous firm. Her professionalism, empathy, and willingness to help made such a stressful situation feel so much easier. If the rest of the team is anything like Phindile, I know I’m in good hands. Thank you for treating me with kindness and making me feel heard. I truly appreciate everything you’ve done.

marianne mattern
2 months ago
Andrew was a very nice person. Unfortunately they did not have shade for the people in the pre register line. Which left people with disabilities and non disabled left in the sun. They did provide little bottles of sunscreen and promo hand fans. Water was provided. Thank you for the kindness.

Rachael Brown
2 months ago
Thanks for your gracious contribution to our community

Jeremiah's Ice of West Melbourne
2 months ago
It was an absolute pleasure to join you this year in project backpack! What a great give-back for our local youth, it was an incredibly smooth event. Great team work!!

Nicole Popun
2 months ago
Thank you for giving back to the community. God bless your family.

Andrew Arnabat
2 months ago
My wife and I got hit with a car accident and the insurance chaos that followed. Tiffany Whitehouse and the Andrew Pickett Law team stepped up. Tiffany was always on the ball and went the extra mile. Vonda, Lindsey, Lauren, and Caroline really cared. They handled everything so we didn’t have to, moved fast, and got us the max they could. No stress. Just results

Joshua Sund
2 months ago
My daughter really enjoyed her backpack everything was very well organized

Audra Forbes
2 months ago
Amazing turnout! Everyone was so helpful, handing out waterbottlesand fans to stave off the scorching heat. I'm glad I stopped by.

Latisha Watkins
2 months ago
It was a pleasure to volunteer with Andrew Pickett Law Firm and his incredible team. I can’t say enough about how amazing his team communicated with me. A wonderful community event. The families that his firm helped at this year’s Back-to-School event was such a rewarding experience. The team was well-organized, welcoming, and made it so easy for me as a volunteer to step right in and make a meaningful impact. Watching the kids get excited about their new backpacks filled with supplies and seeing parents feel supported as the school year begins was the best part of the day. It’s amazing what can happen when a community comes together with a shared goal. I’m so grateful to have been a part of it and definitely look forward to helping out again in the future.

Rahmeik Venable
2 months ago
Wow, any person willing to hold an event to give back is an A1 person to me, the staff was absolutely amazing in organizing, and maintaining a great atmosphere for us all. I'll be looking forward to attending another community event.

Jennifer Cleveland
2 months ago
Lauren and her team are the best! Thank you for all the help, I 10/10 recommended them!

Megan Summers
2 months ago
It was a pleasure meeting Mr. Pickett and everyone at the law firm. From the moment I arrived, I was welcomed with kindness, professionalism, and genuine hospitality. Mr. Pickett took the time to personally greet me, listen attentively, and make me feel valued. What impressed me most was his commitment to giving back to the community, especially through initiatives that support local youth, such as the annual back-to-school backpack drive. It’s inspiring to see a law firm that not only provides excellent service but also makes a meaningful impact beyond the office. I am truly grateful to have had the opportunity to meet Mr. Pickett and his incredible team. Thank you all for your dedication, generosity, and the positive difference you continue to make in the community. I highly recommend this firm to anyone looking for a team that genuinely cares.

Ivanova Rodriguez
2 months ago
Great experience, kindness people
Injured in Titusville? We're Ready to Help.
Andrew Pickett Law has helped thousands of accident victims recover the compensation they deserve. Tell us what happened – we'll take it from there.
Start My Free Case ReviewNo upfront costs. No fees unless we win your case.
Meet Andrew Pickett
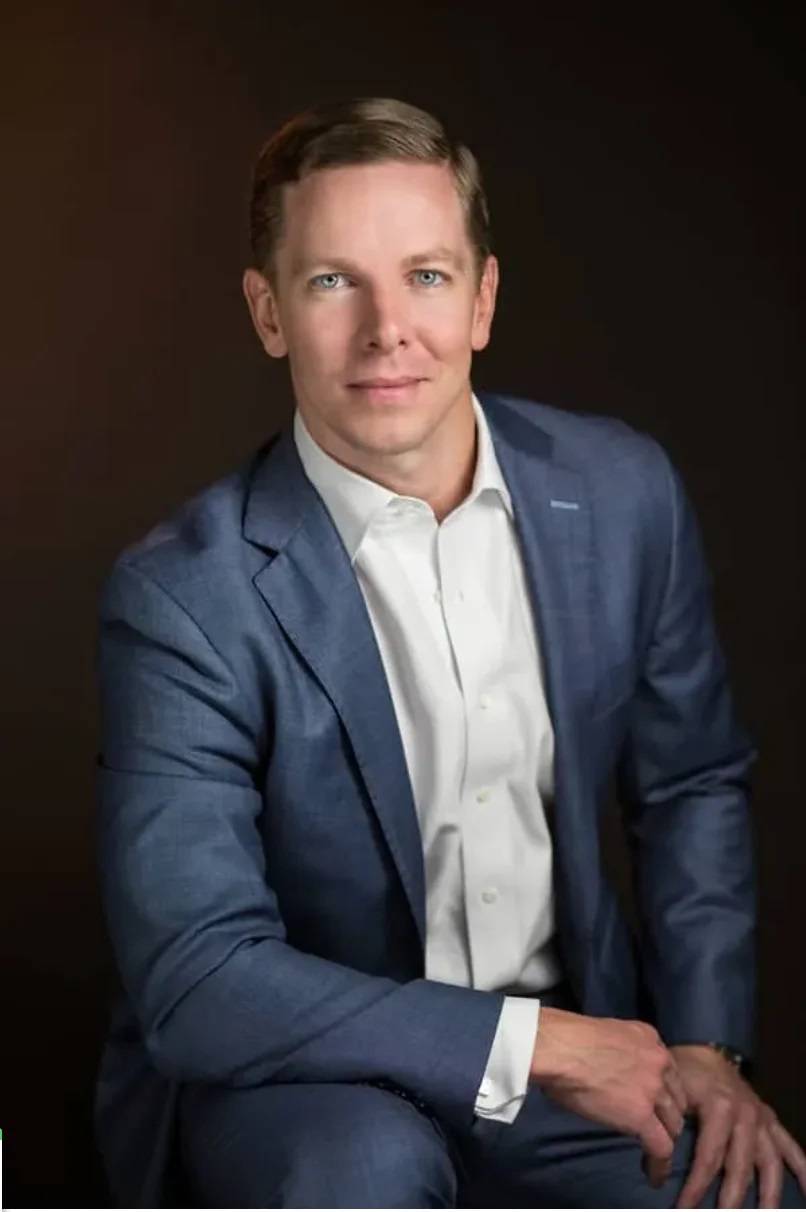
Dealing with the murky policies of insurance companies designed to confuse and prevent you from receiving compensation is our expertise.
15+ years experience as a personal injury attorney.
Specialized in battling insurance companies.
95% settlement rate for clients.
Handled 450+ personal injury cases.
Collected more than $50 million for clients.
450+ people have chosen Andrew as their attorney.